Головна сторінка Державної податкової служби України
 The only state web portal
of electronic services

-
State Tax Service
of Ukraine - Contacts
The only state web portal
Individuals-entrepreneurs and individuals who carry out independent professional activities and have joined defense of Ukraine, can benefit from exemption from paying a number of taxes and single contribution for themselves for a period of military service.
Benefit applies to self-employed individuals who were called up for military service during mobilization or concluded a contract. In this case, they must be registered as individuals-entrepreneurs or self-employed individuals before the moment of conscription or conclusion of the contract.
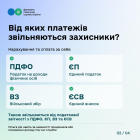
What payments are defenders are exempted from?
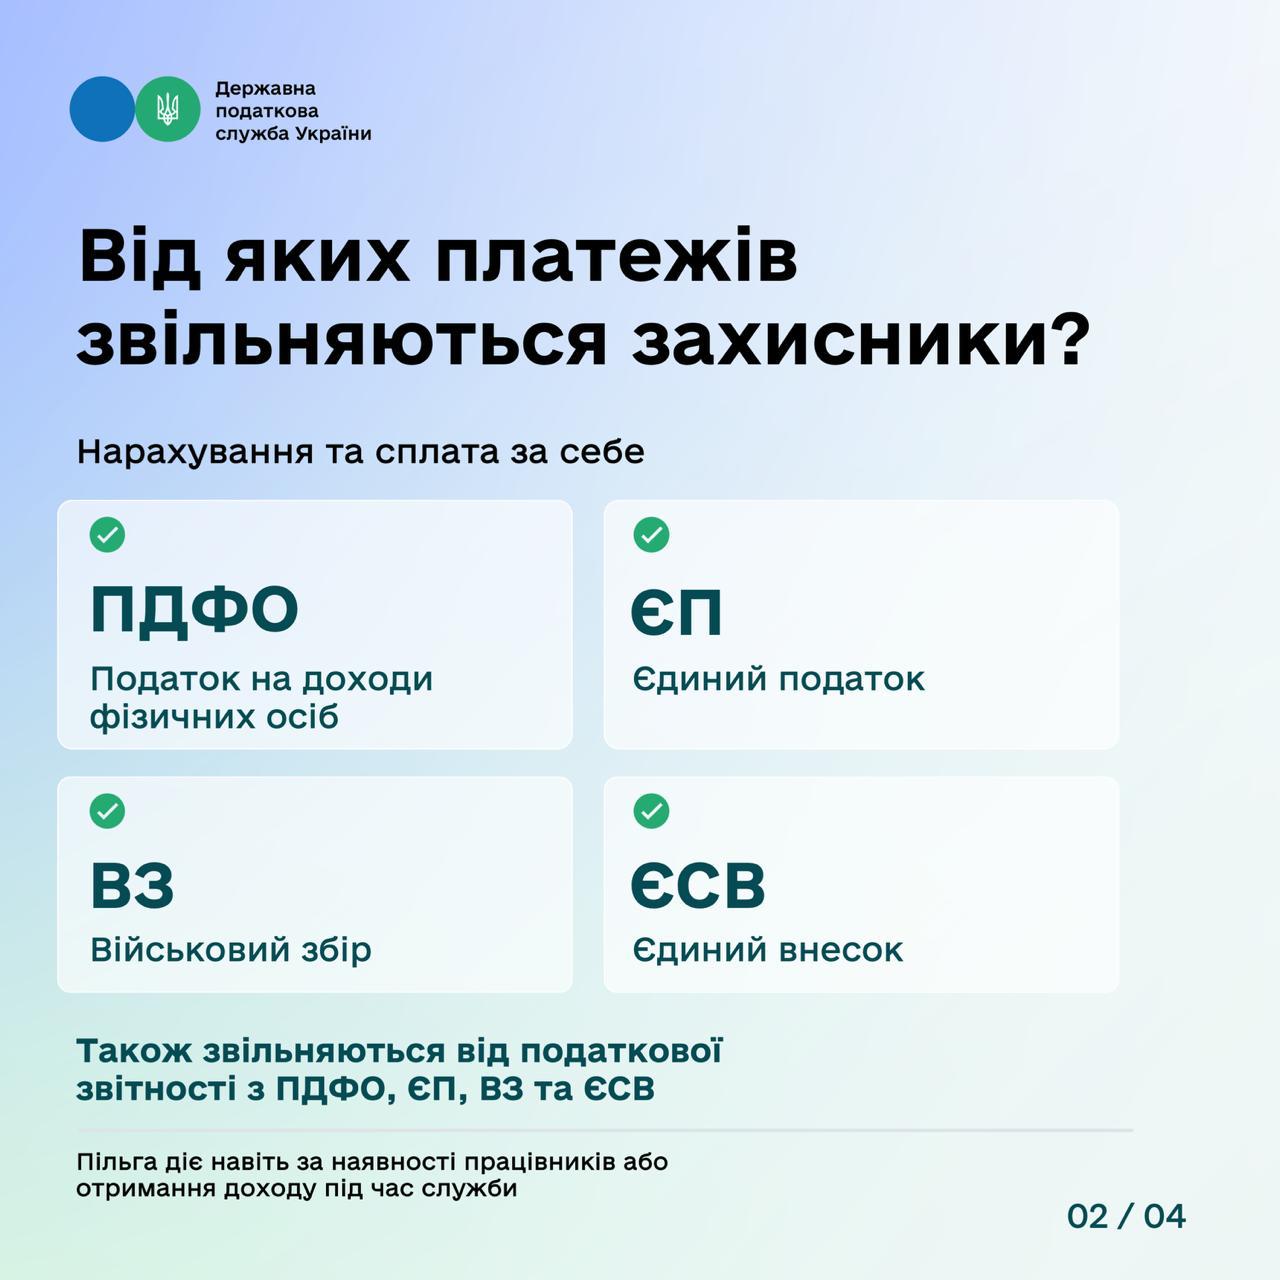
For a period of military service, but not earlier than February 24, 2022, the following individuals are exempted from the obligation for themselves to:
- accrue and pay personal income tax, single tax, military levy;
- submit tax reports on the specified taxes.
Exemption applies even if individual-entrepreneur has employees or continues to receive income from economic activities while performing military service.
Also, single social contribution is not paid if individual-entrepreneur does not have employees.
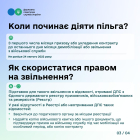
When does the benefit begin to apply?
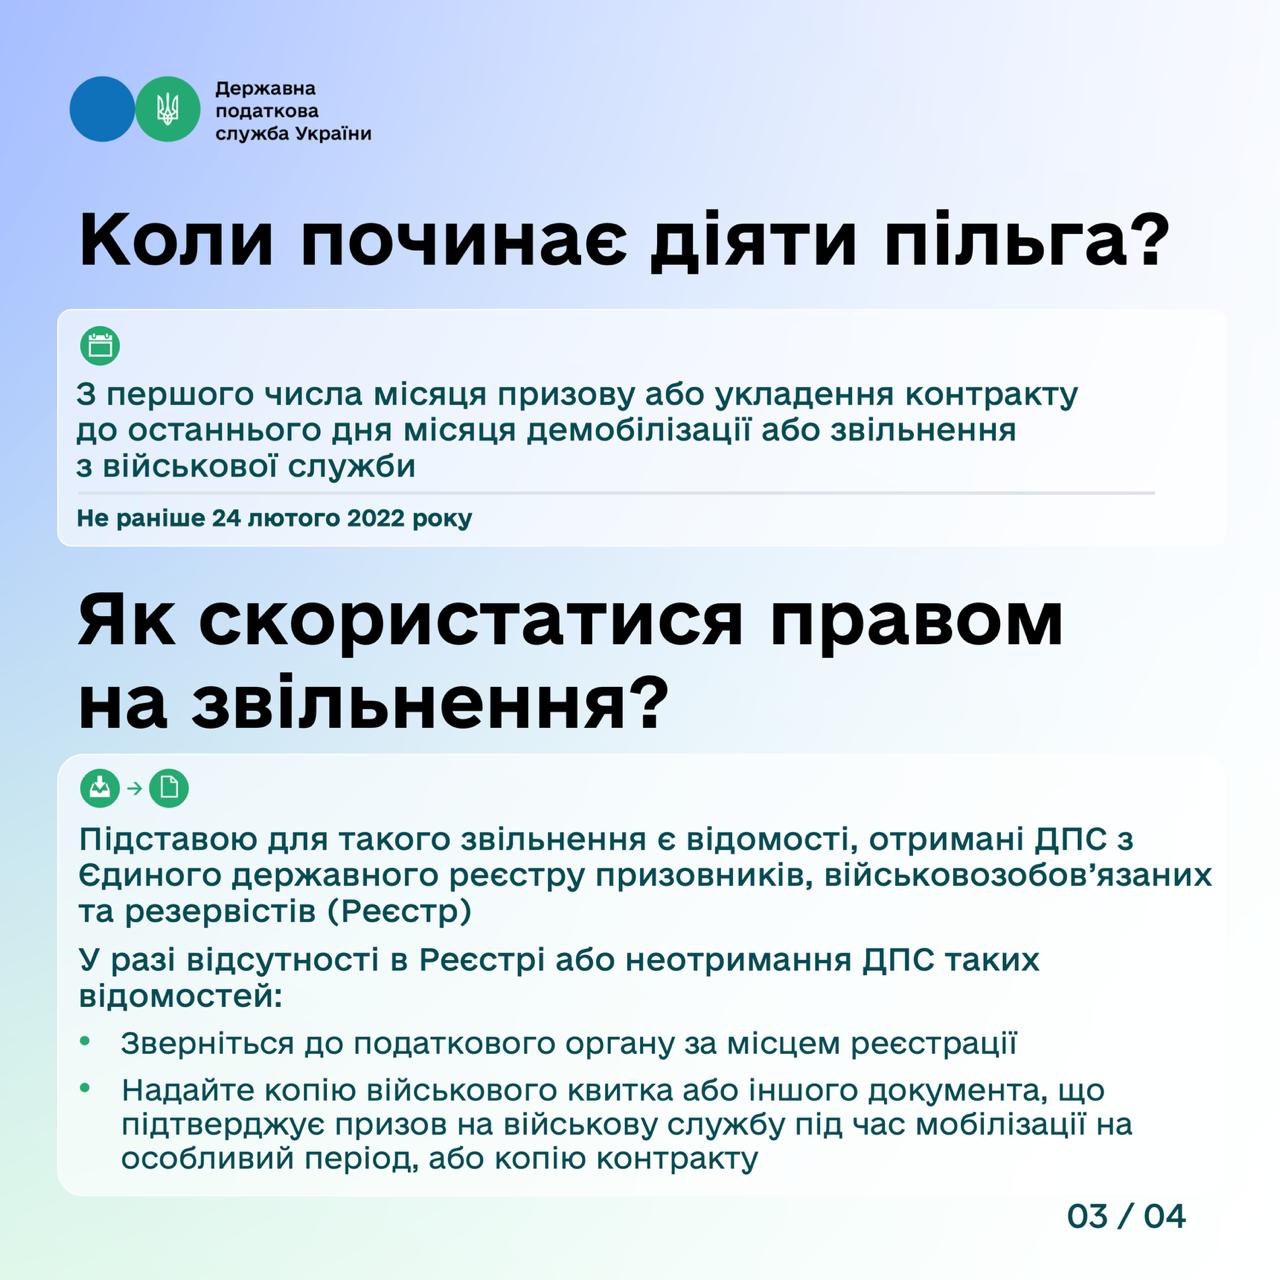
Exemption is valid from the first day of month in which individual was called up for military service or signed the contract, and until the last day of month in which demobilization or discharge from military service took place.
How to exercise right to dismissal?
Basis for such exemption is information received by the State Tax Service from the Unified state register of conscripts, military enlisted persons and reservists (hereinafter – Register) on the date of mobilization, conclusion of the contract, demobilization (discharge from military service) of self-employed individual.
In the absence of information in Register or non-receipt by the central executive body implementing state tax policy about the date of mobilization, conclusion of the contract, mobilized individual-entrepreneur may apply to the tax authority at the registration place and provide a copy of military ID or other document confirming the call-up to military service during mobilization for a special period, or a copy of the contract.
Taxpayer or representative by power of attorney may apply to the tax authority.
Where to get consultation?
If there are any questions about application of benefit or procedure for submitting documents, defenders-entrepreneurs and their representatives can contact the tax authority where they are registered directly.
It is also possible to get clarification at the Tax Consultant Offices working in territorial bodies of the State Tax Service. They will provide practical assistance on taxation questions.
To support defenders-entrepreneurs, in territorial bodies of the State Tax Service also operate special “hotlines” where it is possible to can get consultation.